Decree 70/2025 introduces mandatory electronic PIT withholding document procedures. This guide covers new requirements, issuance timing, document formats, and error handling processes for Vietnam businesses and HR departments.
- Decree 70/2025: Electronic Personal Income Tax Withholding Document Requirements
- Electronic PIT Withholding Documents: Definition and Scope
- Registration and Document Content Requirements
- Document Creation and Issuance Timing
- Document Format Standards and Error Correction
- Transition to Electronic Documents
Decree 70/2025: Electronic Personal Income Tax Withholding Document Requirements
Decree 70/2025/NĐ-CP has fundamentally reformed tax management procedures, particularly for Personal Income Tax (PIT). This guide covers mandatory electronic PIT withholding document regulations under Decree 70/2025, including document forms, issuance timing, and error correction procedures.
Electronic PIT Withholding Documents: Definition and Scope
Electronic PIT withholding documents are created by income-paying organizations or individuals in electronic format to record PIT deductions from employees.
1. Mandatory Effective Date
According to Clause 3, Article 1 of Decree 70/2025/NĐ-CP, all organizations and enterprises must use electronic documents for PIT withholding beginning June 1, 2025.
2. Elimination of Paper Documents
Per Article 3 of Decree 123/2020/NĐ-CP (amended by Decree 70/2025), self-printed and ordered paper documents are officially discontinued. Businesses must use only electronic tax withholding documents, with or without tax authority codes.
Registration and Document Content Requirements
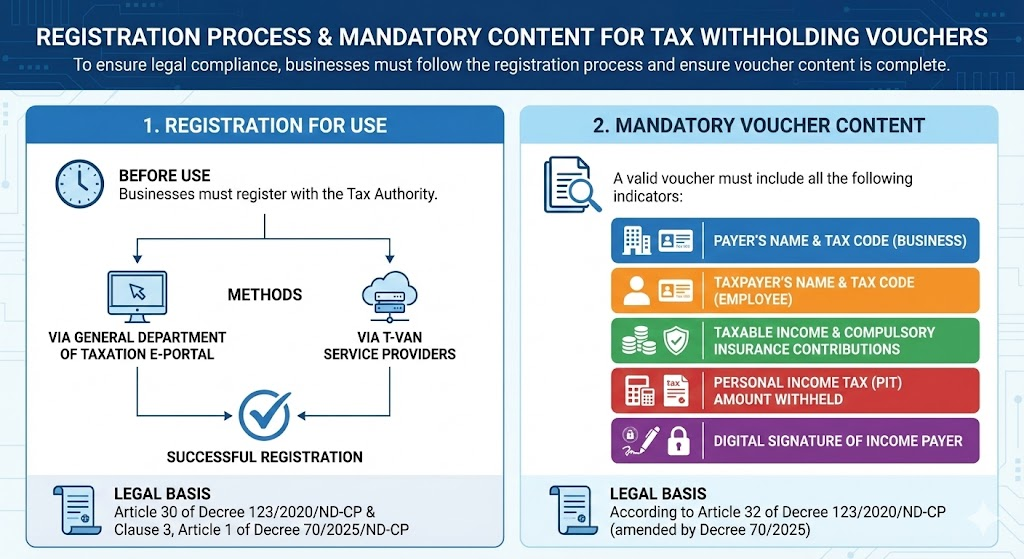
Legal use requires compliance with registration procedures and complete document content.
1. Tax Authority Registration
Before use, businesses must register with tax authorities:
- Method: Register through the General Department of Taxation Web Portal or T-VAN service providers;
- Legal basis: Article 30 of Decree 123/2020/NĐ-CP and Clause 3, Article 1 of Decree 70/2025/NĐ-CP.
2. Required Document Content
Valid tax withholding documents must include all criteria per Article 32 of Decree 123/2020/NĐ-CP (as amended):
- Income payer name and tax code (business);
- Taxpayer name and tax code (employee);
- Taxable income amount and mandatory insurance payment amount;
- PIT withheld amount;
- Digital signature of the income payer.
Document Creation and Issuance Timing
Accounting and HR departments must pay special attention to timing requirements to avoid violations.
1. Creation Timing
Per Article 31 of Decree 123/2020/NĐ-CP and Clause 1, Article 1 of Decree 70/2025/NĐ-CP, income-paying organizations must create the tax withholding document and digitally sign it immediately upon PIT withholding or when requested by the employee.
2. Issuance Timing
Document issuance timing varies by employment contract type per Point i, Clause 1, Article 25 of Circular 111/2013/TT-BTC:
- Employees without labor contracts or with contracts under 3 months: Businesses may issue separate documents for each deduction or provide consolidated documents for multiple deductions in a tax period (e.g., a single year-end summary document);
- Employees with labor contracts of 3 months or longer: Businesses issue the tax withholding document once per tax period (typically year-end) upon the employee’s request.

Document Format Standards and Error Correction
Decree 70/2025 and Appendix III of Decree 123/2020/NĐ-CP standardize document symbols:
1. Form and Symbol Requirements
- Document type: Personal Income Tax Withholding Document;
- Form number: 03/TNCN;
- Form symbol: 01/CTKT (01 = form version);
- Document symbol: CT/25E (25 = creation year 2025, E = electronic document designation);
- Serial number: Maximum 7 digits, starting at 0000001.
2. Error Correction Procedures
When tax withholding documents contain errors, businesses follow Article 34 of Decree 123/2020/NĐ-CP and new guidance in Decree 70/2025:
- Do Not Cancel: Unlike invoices, electronic tax withholding documents with errors are not canceled if already sent to the taxpayer;
- Create Replacement Document: Businesses must document the error in a written agreement with the employee, then issue a new tax withholding document replacing the erroneous one. The new document must state: “Replacement for document form number… symbol… number… date… month… year…”.
Transition to Electronic Documents
The mandatory transition to electronic PIT withholding documents under Decree 70/2025 is effective June 1, 2025. Businesses must proactively review technology infrastructure, register with tax authorities, and master creation timing and issuance rules to ensure legal compliance and avoid administrative penalties during tax settlement.
For compliance guidance, contact Wacontre Accounting Services via telephone (028) 3820 1213 or email [email protected]. Our experienced team specializes in Vietnam tax compliance, accounting, and company formation. Japanese-speaking clients may call (050) 5534 5505.