The replacement record for erroneous e-invoices under Decree 70/2025/ND-CP has been updated with new and valid processing procedures. This document is essential for businesses to correctly handle invoice errors in compliance with regulations. Below is a detailed guide on how to apply replacement records and adjustment records for e-invoices in line with the latest standards.
What is an adjustment record for erroneous e-invoices under Decree 70/2025/ND-CP?
An adjustment record for an erroneous e-invoice is a document that records the agreement between the seller and the buyer when errors are discovered in an already issued e-invoice that needs to be replaced with a new one.
According to Point b, Clause 2, Article 19 of Decree 123/2020/ND-CP, as amended by Clause 13, Article 1 of Decree 70/2025/ND-CP:
“Before adjusting or replacing erroneous e-invoices as prescribed at Point b of this Clause, where the buyer is an enterprise, economic organization, other organization, business household, or individual business, the seller and buyer must prepare a written agreement clearly stating the error. If the buyer is an individual, the seller must notify the buyer or post the notification on the seller’s website (if any). The seller shall retain the written agreement and present it upon request.”
Handling e-invoice errors under Decree 70/2025/ND-CP
1. Abolition of the e-invoice cancellation requirement
Previously, under Decree 123/2020/ND-CP, when errors were found in issued e-invoices, businesses were required to cancel the erroneous invoice and issue a new one.
However, Clause 13, Article 1 of Decree 70/2025/ND-CP, which amends Article 19 of Decree 123/2020/ND-CP, specifies that erroneous e-invoices no longer need to be canceled. Instead, businesses must adjust or replace the incorrect e-invoice.
2. Handling errors in e-invoices
Where the company name or the buyer’s address is incorrect, but the tax code is accurate and tax obligations are not affected:
– The seller must notify the tax authority of the erroneous e-invoice using Form 04/SS-HDDT via the enterprise’s e-invoice system.
– Notify the buyer. No new invoice needs to be issued.
If the errors involve the tax code, product price, VAT rate, tax amount, or incorrect product/service descriptions, the seller may choose to issue either an adjustment invoice or a replacement invoice.
Guide to preparing an adjustment record for e-invoices under Decree 70/2025/ND-CP
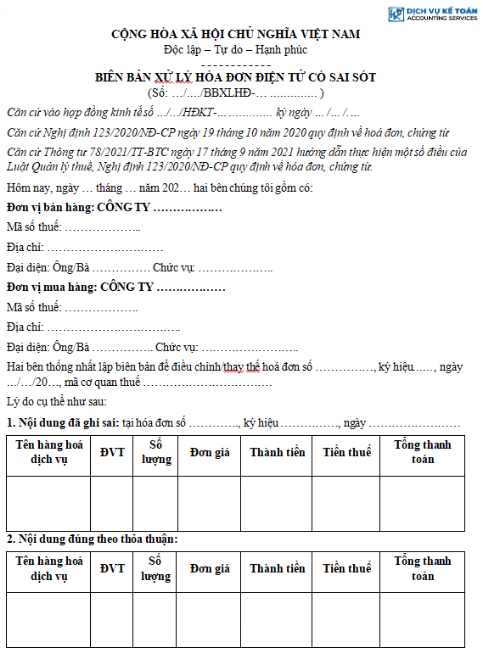
1. Latest adjustment record template
Businesses must use a template that complies with current regulations. The adjustment record should include the following:
– Information of the seller and buyer
– Details of the original invoice (number, code, issue date)
– Description of the error
– Corrected or replacement content
– Confirmation and signature of both parties
2. Important notes
It is mandatory to prepare an adjustment record between the seller and buyer before making any adjustments or replacements (for organizations, businesses, and business households).
Businesses may issue a single adjustment or replacement invoice covering multiple erroneous invoices issued in the same month for the same customer.
If a particular handling method (adjustment or replacement) has already been applied to an invoice, subsequent handling must follow the same method. Switching from adjustment to replacement, or vice versa, is not permitted.
3. Timing and deadline for preparing the record under Decree 70/2025/ND-CP
Decree 70/2025/ND-CP does not set a specific time limit for adjusting or replacing an e-invoice after an error is detected.
However, to ensure compliance and avoid legal risks, the seller should carry out the adjustment or replacement as soon as possible after detecting the error and completing the written agreement with the buyer.
Responsibilities and penalties for failing to prepare adjustment records

1. Responsibilities of the seller and the buyer
– The seller is primarily responsible for reviewing, detecting errors, and contacting the buyer to prepare the adjustment record.
– The buyer must cooperate to confirm the error and sign the adjustment record.
– Both parties must retain the documentation as required by law.
2. Administrative penalties under Decree 70/2025/ND-CP
Applicable penalties may include:
– A fine of VND 2,000,000 to VND 5,000,000 for failing to prepare an adjustment record for invoice errors.
– A fine of up to VND 10,000,000 if the error affects tax obligations and no adjustment record is prepared.
– Depending on the severity, the tax authority may require re-filing or impose tax assessments.
The adjustment record for erroneous e-invoices is a critical legal tool that enables businesses to promptly correct errors without affecting their tax obligations. A clear understanding of Decree 70/2025/ND-CP helps ensure proper procedures, avoid penalties, and promote transparency in accounting and financial operations.
For any inquiries, please contact Wacontre Accounting Services via Hotline: (028) 3820 1213 or email [email protected] for prompt assistance. With a team of experienced professionals, Wacontre is committed to providing dedicated and efficient service. (For Japanese clients, please contact Hotline: (050) 5534 5505).
Click here to register and access the form.