A clear guide to accounting for free promotional goods under Vietnam’s current accounting and tax regulations. Properly recording promotional items is a critical task for every corporate accountant. This article explains in detail how to handle “free promotional goods” and “gifted goods” in line with the latest Vietnamese accounting standards.
What is the accounting treatment for free promotional goods?
The accounting treatment for free promotional goods refers to recording in the books any transaction in which a company provides goods at no charge to customers for promotional, marketing, or customer-appreciation purposes.
While this is a common business practice, both the accounting entries and tax recognition must comply with the law to ensure costs are legitimate and to avoid errors in tax declarations.
Common types of promotional goods in enterprises
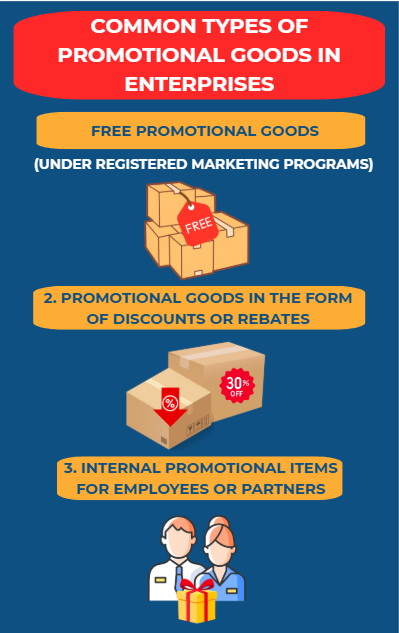
1. Free promotional goods under a registered marketing program
This refers to goods given away without payment as part of a promotional program that has been registered with the competent authorities. In this case, the business may issue an invoice with a value of zero and is not required to recognize revenue. The cost of the goods can still be recorded under selling expenses, provided it is supported by valid documentation.
2. Promotional goods in the form of discounts or rebates
Some businesses do not give products away directly, but instead offer discounts or rebates after purchase. These are not considered “free promotional goods” but rather adjustments to revenue. Accountants must clearly distinguish between the two to ensure correct treatment.
3. Internal promotional goods for employees or partners
When a company gives goods to employees, agents, or partners without collecting payment, the transaction is not part of a registered marketing program. It should therefore be recorded as a welfare or gift expense, and the business must issue an invoice and calculate VAT accordingly.
Read more: Criteria for determining reasonable costs for enterprises according to the latest regulations
Accounting and tax regulations for promotional goods
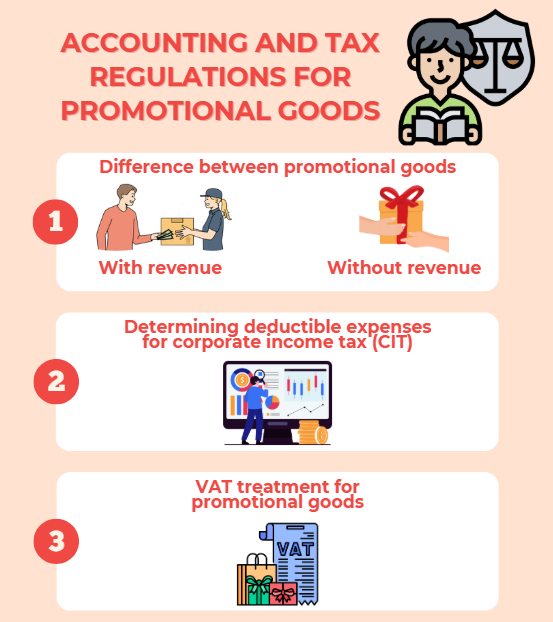
1. Difference between promotional goods with and without revenue
- Promotional goods with revenue: Recognize revenue and record entries as normal.
- Promotional goods without revenue: Do not recognize revenue; record the related costs separately under the promotional program.
2. Determining deductible expenses for corporate income tax (CIT)
Only promotional expenses that follow a registered program and are supported by valid documentation can be deducted when calculating taxable income.
3. VAT treatment for promotional goods
– For valid promotions under the Law on Commerce: no output VAT declaration is required.
– For gifts outside a promotional program: output VAT must be declared based on the taxable price of similar goods.
Detailed accounting entries for each case of promotional goods
1. Accounting entry for free promotional goods
When promotional goods are issued without collecting payment:
– Debit Account 641 (Selling expenses)
– Credit Account 156 (Inventory – goods)
At the same time, issue an invoice with zero value if the promotion has been registered.
2. Accounting for gifts with a VAT invoice
When goods are given outside a registered promotion:
– Debit Account 641 or 642 depending on the nature of the expense
– Debit Account 3331 (VAT payable)
– Credit Account 512 (Internal revenue) or equivalent
– Credit Account 511 in special cases
– Credit Account 156 (Inventory – goods issued)
Key points on invoicing and tax declaration
1. How to record promotional goods on VAT invoices
– For registered promotions: clearly state on the invoice “promotional goods under program no…”, with a unit price of 0 and a VAT rate of 0%.
– Avoid recording a positive price and then applying a 100% discount, which may be misinterpreted as a price reduction.
2. Handling errors or missing promotional invoices
– If an invoice was missed: issue a supplementary invoice immediately.
– If the promotional details were incorrect: issue a correction document together with a revised invoice.
Accounting for free promotional goods requires a thorough understanding of the relevant regulations and of the nature of each transaction. Businesses must ensure accurate invoicing, proper bookkeeping, and correct tax declarations in every scenario. Doing so not only prevents tax risks but also helps manage promotional expenses and revenue more effectively.
For any inquiries, contact Wacontre Accounting Services via Hotline: (028) 3820 1213 or email [email protected] for prompt assistance. With a team of experienced professionals, Wacontre is committed to providing dedicated and efficient service. (For Japanese clients, please contact Hotline: (050) 5534 5505).