Form 24/DK-TCT enables businesses to terminate their tax code legally and efficiently. This document is mandatory for any business or individual seeking to deactivate a tax code in Vietnam. This article provides a step-by-step guide on how to complete and submit the form correctly.
Form 24/DK-TCT: Request for Termination of Tax Code Validity
A tax code is the identification number issued by the tax authority to a business upon establishment, used to fulfill all tax declaration obligations. When a business decides to cease operations and dissolve in accordance with the law, terminating the validity of its tax code becomes a required step.
The latest version of Form 24/DK-TCT, issued under Circular No. 86/2024/TT-BTC, applies to organizations and businesses that wish to deactivate their tax codes at a specific point in time.
Termination of Tax Code Validity: Definition and Conditions
1. What Termination of Tax Code Validity Means
Terminating a tax code means the tax authority officially records that the business’s tax code is no longer active in its management system. From that moment, the business is no longer required to declare, pay taxes, or carry out any tax procedures linked to that code.
Common cases of tax code termination include:
– Businesses undergoing dissolution, bankruptcy, or merger that wish to cease operations
– Dependent units (branches, representative offices, business locations, etc.) dissolving or ceasing operations at the parent company’s request
– Sole proprietorships ending business activities
– Foreign organizations terminating their operations in Vietnam
2. Conditions for Termination of Tax Code Validity
To terminate a tax code, the organization or enterprise must have completed tax finalization with the tax authority and have no outstanding tax obligations going forward. Specifically:
– The enterprise and its dependent units have actually ceased operations and no longer engage in real economic transactions.
– The enterprise has completed the dissolution dossier and procedures at the business registration office (Department of Planning and Investment).
– All bank accounts opened by the enterprise during its operations have been closed.
– Tax finalization with the tax authority has been completed: all tax reports submitted, outstanding tax amounts settled, and accounting data and books reconciled up to the cessation date.
Step-by-Step Guide to Completing Form 24/DK-TCT
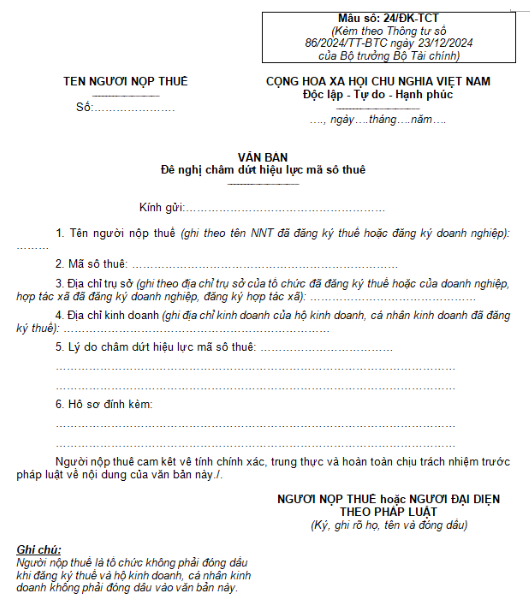
Form 24/DK-TCT contains the following main sections:
– Enterprise information (name, tax code, address, etc.)
– Reason for terminating the tax code (state the specific reason clearly: dissolution, bankruptcy, cessation of business, etc.)
– Taxpayer’s commitment, signature, and company seal
Place of submission: the tax authority that directly manages the enterprise. The assigned tax officer will verify and reconcile all tax obligations before confirming the termination of the tax code.
Important notes:
– All tax reports must be completed and related obligations settled in full.
– Once terminated, the tax code cannot be reused.
– Keep the tax authority’s confirmation documents for future reference.
Submitting Form 24/DK-TCT is a critical step in the process of winding down business operations or ending tax obligations in Vietnam. Individuals and organizations must follow the correct procedures, complete all required information, and ensure that tax obligations are fully settled before requesting termination. This not only ensures legal compliance but also allows the business to close in an orderly and transparent manner under Vietnamese law.
For any inquiries, please contact Wacontre Accounting Services via Hotline: (028) 3820 1213 or email [email protected] for prompt assistance. With a team of experienced professionals, Wacontre is committed to delivering dedicated and efficient service. (For Japanese clients, please contact Hotline: (050) 5534 5505).
Click here to register and download the form.

EDITORIAL INFORMATION
Wacontre Accounting & Tax Editorial Team
This article is maintained by the Wacontre editorial team. A named reviewer and review date are shown only after individual sign-off; this article does not yet have that sign-off.
Official references
Update history
- : Added editorial ownership, official references, and update history; no individual expert review is claimed.
- : Originally published.