Value Added Tax (VAT) is a core part of Vietnam’s tax system. It is an indirect tax imposed on the added value of goods and services across the production and consumption cycle. A solid understanding of VAT helps businesses stay compliant, optimize tax costs, and improve operational efficiency. This article provides essential and up-to-date information on VAT, including its definition, calculation methods, and current legal framework in Vietnam.
What Is Value Added Tax (VAT)?
Definition of VAT
Value Added Tax (VAT), known in Vietnamese as “Thuế Giá Trị Gia Tăng” (GTGT), is an indirect tax levied on the added value of goods and services at each stage of production and distribution. Businesses collect VAT on behalf of the government through the sale of goods and provision of services. In practice, consumers bear the VAT when they purchase goods or services, while businesses are responsible for remitting it to the tax authorities. VAT has been applied in Vietnam for many years and plays a significant role in securing state budget revenue and promoting transparency in business activities.
Key Characteristics of VAT
- Indirect taxation: VAT is an indirect tax, which means the final tax burden falls on the end consumer, while businesses act as intermediaries that remit the tax to the government. This structure makes tax collection more efficient and reduces the risk of tax evasion.
- Levied on added value: VAT is calculated based on the value added at each stage of the supply chain, from production to final consumption. This is what sets it apart from other taxes such as excise tax or import-export duties.
History and Role of VAT
VAT was first introduced in France in the 1950s and quickly became a globally adopted tax model. Its core role is not only to generate revenue for the state budget but also to encourage transparency in economic activities. In Vietnam, VAT was officially implemented in 1999 and has since become one of the key pillars of public finance, supporting economic development and improvements to public infrastructure.
Differences Between VAT and Other Taxes
One of the main differences between VAT and other taxes lies in the collection mechanism. VAT is applied at every stage of the supply chain, from production to consumption, whereas taxes such as excise tax are imposed only on specific goods. VAT also encourages transparency because businesses must issue invoices to claim input tax deductions, which improves control and reduces tax fraud.
Cases Subject to VAT
Goods and Services Subject to VAT
Most goods and services in Vietnam are subject to VAT, ranging from food and clothing to services such as transportation and telecommunications. However, the VAT law also defines exemptions, including education, healthcare services, and imported goods used for humanitarian aid. Understanding this list helps businesses and consumers recognize their rights and obligations and avoid penalties caused by misunderstanding.
VAT Exemptions
VAT exemptions apply to specific goods and services in order to support priority sectors such as healthcare, education, and scientific research. In addition, projects in agriculture or clean energy production may also qualify for VAT exemptions to promote sustainable development. Keeping up to date with exemption regulations helps businesses optimize operating costs.
Latest Regulations on VAT Liability
Under the latest regulations, not only corporate entities but also small-scale individual businesses are subject to VAT. This broadens the tax base and ensures fairness in taxation. However, small businesses with annual revenue below VND 100 million may qualify for VAT exemptions or be taxed under a simplified direct method.
Benefits of VAT for the Economy
VAT directly contributes to state revenue while promoting transparency and accountability in business activities. Its application enables tax authorities to monitor commercial activity more effectively and encourages businesses to improve productivity and product quality in order to add value.
VAT Calculation Methods in Detail
Tax Deduction Method
The tax deduction method is widely used, particularly by larger enterprises with stable revenues. Under this method, the VAT payable is calculated as follows:
VAT Payable = Output VAT − Input VAT
Businesses must keep proper invoices and valid supporting documents to secure their right to deductions. This method encourages transparency in business operations and strengthens overall financial management.
Direct Calculation Method
This method is typically applied to small household businesses or enterprises that do not meet the conditions for the deduction method. The VAT payable is calculated by multiplying revenue by a specified percentage. For example:
- Construction services without material supply: 5% VAT rate.
- Manufacturing or transportation activities: 3% VAT rate.
While simpler, this method offers less incentive for businesses to professionalize their operations and expand.
Current VAT Rates
Vietnam currently applies three main VAT rates:
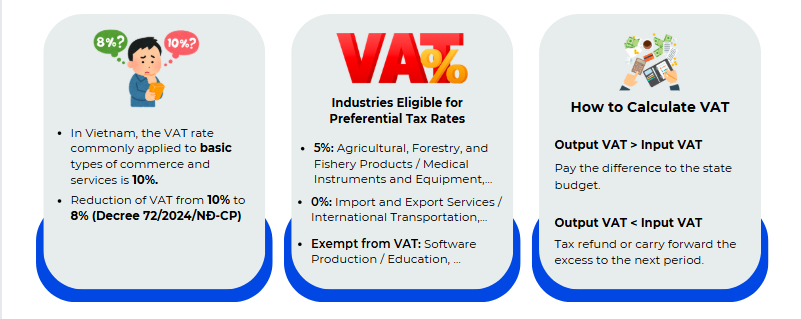
Practical VAT Calculation Example
A manufacturing business sells products at a pre-VAT price of VND 200 million. At a 10% VAT rate:
Output VAT = VND 200 million × 10% = VND 20 million.
If the business has purchase invoices with input VAT of VND 5 million, the VAT payable is:
VAT Payable = VND 20 million − VND 5 million = VND 15 million.
This straightforward calculation supports compliance and financial accuracy.
VAT Refunds: Regulations and Conditions
Cases Eligible for a VAT Refund
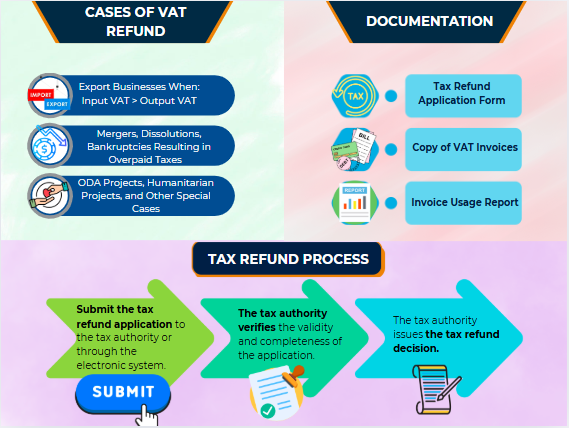
VAT refunds apply in the following cases:
- Export businesses where input VAT exceeds output VAT.
- Mergers, dissolutions, or bankruptcies that result in overpaid taxes.
- Special cases regulated by the tax authorities, such as projects funded by ODA or humanitarian aid.
VAT Refund Process
The VAT refund process generally includes the following steps:
- The business submits the tax refund application to the tax authority or through the electronic filing system.
- The tax authority verifies the validity and completeness of the application.
- If eligible, the tax authority issues the tax refund decision.
The process requires strict adherence to regulations to avoid rejection.
Required Documents and Procedures
A VAT refund application must include:
- A tax refund request form (using the official template).
- Copies of VAT invoices and related supporting documents.
- An invoice usage report.
All documents must be carefully and accurately prepared to prevent errors during processing.
Tips to Avoid Mistakes During a VAT Refund
- Make sure invoices and related documents are valid and match the figures in the tax reports.
- Stay up to date on changes in tax policy in order to proactively manage financial compliance.
Value Added Tax (VAT) is not only an essential financial tool, but also a reflection of how transparent and responsible a business is in its operations. A clear understanding of VAT calculation, taxable entities, and refund procedures helps businesses comply with the law while leveraging tax policy to optimize costs. For further information or support, please contact our team of experts for timely and detailed guidance.
Learn more:
Corporate Income Tax (CIT): Proper Understanding and Optimizing Efficiency
Personal Income Tax: Definition and Calculation Methods
For any inquiries, please contact Wacontre Accounting Services via Hotline: (028) 3820 1213 or email [email protected] for prompt assistance. With an experienced team of professionals, Wacontre is committed to providing dedicated and efficient service. (For Japanese clients, please contact Hotline: (050) 5534 5505).

EDITORIAL INFORMATION
Wacontre Accounting & Tax Editorial Team
This article is maintained by the Wacontre editorial team. A named reviewer and review date are shown only after individual sign-off; this article does not yet have that sign-off.
Official references
Update history
- : Added editorial ownership, official references, and update history; no individual expert review is claimed.
- : Originally published.