Learn about Form 08/CK-TNCN, the latest personal income tax (PIT) commitment form that helps employees avoid unnecessary tax withholding. Updated under the latest legal regulations, it is a key document in the annual PIT finalization dossier.
What is Form 08/CK-TNCN?
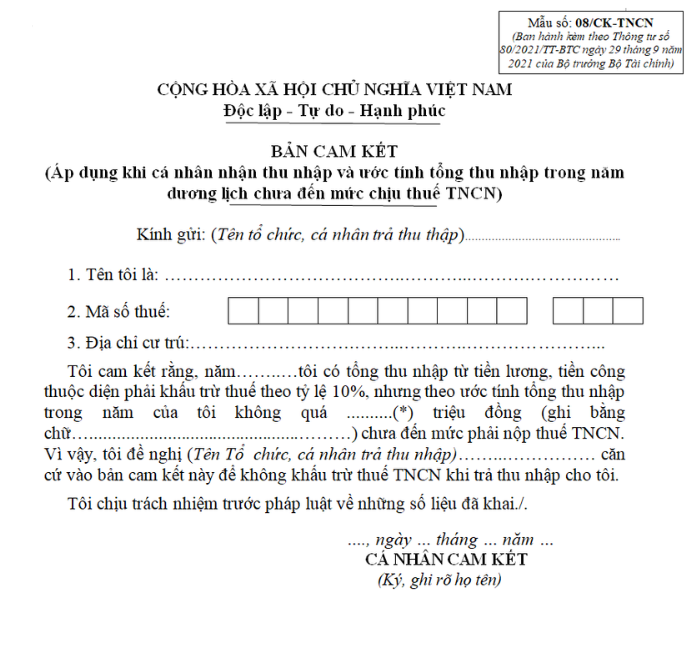
Form 08/CK-TNCN, issued under Circular No. 80/2021/TT-BTC, is a commitment form used to request exemption from personal income tax (PIT) withholding for individuals whose income does not reach the taxable threshold.
Eligible employees may submit this form to their income-paying organization to avoid unnecessary tax withholding.
The form not only reduces the tax burden on employees but also ensures transparency during the annual PIT finalization process.
Who is eligible to use Form 08/CK-TNCN?
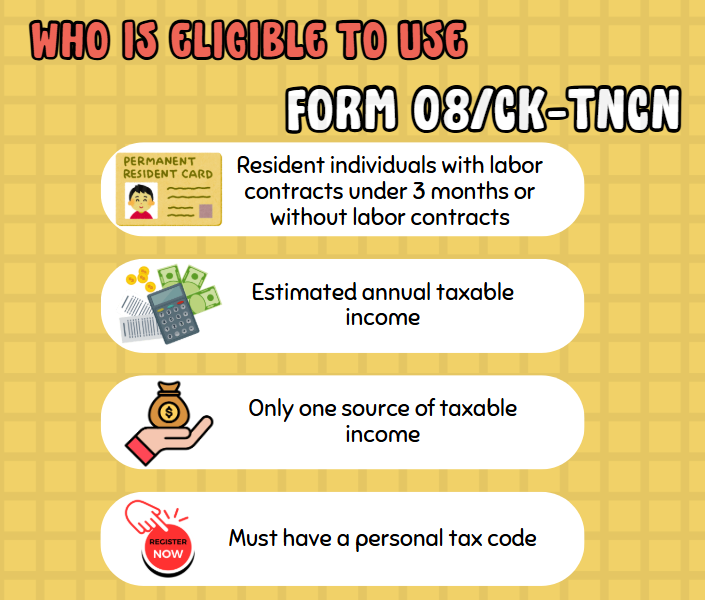
The use of Form 08/CK-TNCN is governed by legal regulations and applies only to individuals who meet all of the following conditions:
1. Resident individuals with labor contracts under 3 months or without labor contracts
The income commitment applies only to tax residents of Vietnam.
⇒ Non-resident individuals are not eligible to make a PIT exemption commitment.
Residents who sign short-term contracts of under 3 months, or who work under service, probationary, internship, or task-based agreements (rather than standard labor contracts), may use this form.
⇒ Individuals with labor contracts of 3 months or more, or indefinite-term contracts, are not eligible to make this commitment.
2. Estimated annual taxable income
The individual must estimate that their total annual taxable income, after family deductions (personal and dependent deductions), does not reach the taxable threshold.
For individuals with no dependents, the threshold is VND 132,000,000 per year. For those with dependents, an additional VND 4,400,000 per dependent is deducted, with no cap on the number of dependents.
3. Only one source of taxable income
The individual must earn income only from a single employer (salary or wages) and have no other income from any source during the year. The total income must be VND 2,000,000 or more per payment.
4. Must hold a personal tax code
The individual must be registered with the tax authority and hold an active tax code at the time of submitting the commitment form.
Obligations of the enterprise or income-paying organization
The employer is responsible for providing legal guidance, supporting procedures, and helping employees submit Form 08/CK-TNCN when needed.
Upon receiving the form, the company will pay salaries without PIT withholding in accordance with the law.
At year-end, the enterprise must consolidate all individuals who submitted the commitment and declare them in Appendix 05-2/BKQTT-TNCN of the PIT Finalization declaration. The declaration must be filed via the electronic tax system within 90 days from the end of the calendar year.
Key notes when preparing Form 08/CK-TNCN
1. Submission timing
The form must be prepared and submitted before the income-paying organization makes any salary payment, that is, before any PIT is withheld. Late or incorrectly submitted forms may result in tax being withheld and declared by the employer in accordance with regulations.
2. Meet all conditions
The individual must meet all four conditions above to use this form. Otherwise, the employer must apply standard PIT withholding to the employee’s income.
3. Legal responsibility
If an individual provides false information in the commitment, resulting in incorrect tax declaration or non-payment, they may face administrative fines, tax recovery, or legal action depending on the severity of the violation.
Form 08/CK-TNCN plays a vital role in protecting employees from improper PIT withholding. Understanding the eligibility criteria, timing, and submission process can help prevent future disputes, tax recovery, and penalties. Enterprises should guide their employees to use this form in compliance with regulations and avoid legal risks.
For any inquiries, contact Wacontre Accounting Services via Hotline: (028) 3820 1213 or email [email protected] for prompt assistance. Backed by a team of experienced professionals, Wacontre is committed to dedicated and efficient service. (For Japanese clients, please contact Hotline: (050) 5534 5505).
Register now to get the form here.

EDITORIAL INFORMATION
Wacontre Accounting & Tax Editorial Team
This article is maintained by the Wacontre editorial team. A named reviewer and review date are shown only after individual sign-off; this article does not yet have that sign-off.
Official references
Update history
- : Added editorial ownership, official references, and update history; no individual expert review is claimed.
- : Originally published.